
Claims lacking proper documentation have a 40% higher chance of delay or denial, and poorly documented evidence can add an average of 23 days to resolution time (claims documentation guidance). When water is spreading across a floor, smoke is staining walls, or a storm has opened the roof, document the loss immediately, then perform only the emergency work needed to prevent additional damage.
You're standing in a damaged room with a phone in one hand and a cleanup number in the other. The instinct is understandable: move soaked furniture, pull up wet flooring, wipe away soot, or call someone to board up the opening. But the first condition of the property may be the clearest evidence you'll have.
The right approach isn't to choose between protecting the building and protecting the claim. It's to record what happened before conditions change, then document every necessary action that follows.
Why Insurance Claim Documentation Actually Matters
A burst pipe can turn a familiar room into an evidence problem within minutes. Water moves under flooring, stains baseboards, and changes the appearance of drywall. A kitchen fire leaves soot, odor, and damaged contents in a scene that may need immediate stabilization. If you clean first and record later, the adjuster may never see the original extent of the loss.
That matters because the insurer must evaluate what was damaged, how it was damaged, when it happened, and what work was necessary. Photos, videos, receipts, estimates, and written notes give the claim a verifiable record. Without them, the claim depends more heavily on memory and later reconstruction.
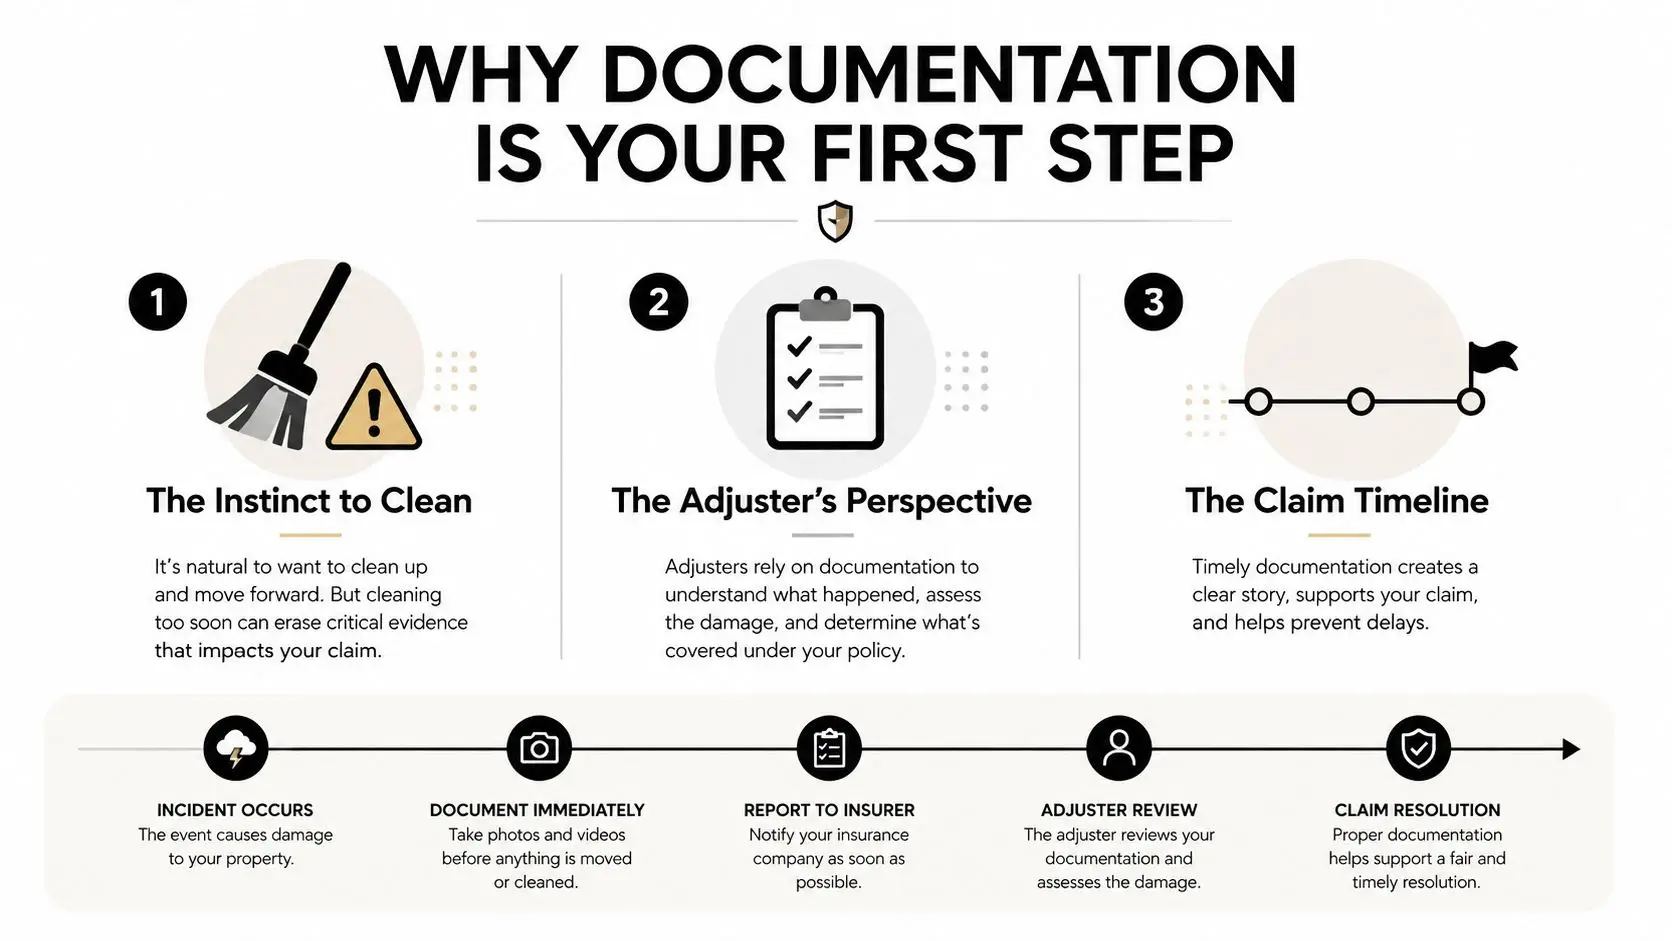
The adjuster needs a timeline, not a story
A verbal explanation can describe the loss, but it rarely proves the full scope. A dated image showing water at the base of a cabinet, followed by a mitigation photograph showing the cabinet removed, creates a clear sequence. An invoice then connects the physical work to a cost.
Florida's claim-handling statute shows how seriously insurers must treat dates. Insurers must acknowledge claim communications within 7 calendar days, begin a reasonably necessary investigation within 7 days after receiving proof-of-loss statements, and complete a physical inspection within 30 days of receiving those statements. The statute also requires dated records for communications, proof of loss, information requests, inspections, estimates, and final payment or denial (Florida claim-handling statute).
Practical rule: If an event, conversation, inspection, estimate, or repair happened, record the date and preserve the supporting file.
Your documentation also needs to reflect the policy. Coverage terms, exclusions, deductibles, and duties after loss can change what evidence matters, so review your policy or use a plain-language guide such as how to read a homeowners insurance policy.
The same principle applies outside the home. If a tree damages a roof or structure, documenting both the property damage and the source condition can help organize the claim file. A specialized resource on insurance claim tree services can help property owners understand what records to request from a tree contractor.
Insurance claim documentation isn't clerical clutter. It's the factual framework that lets the insurer test causation, scope, ownership, necessity, and timing without guessing.
Documenting Damage Before You Start Cleanup
Start with safety. Don't enter a fire-damaged structure, active electrical hazard, contaminated area, or unstable room until the appropriate professionals say it's safe. Once you can document safely, preserve the scene before moving contents or changing surfaces, unless immediate action is required to stop additional damage.
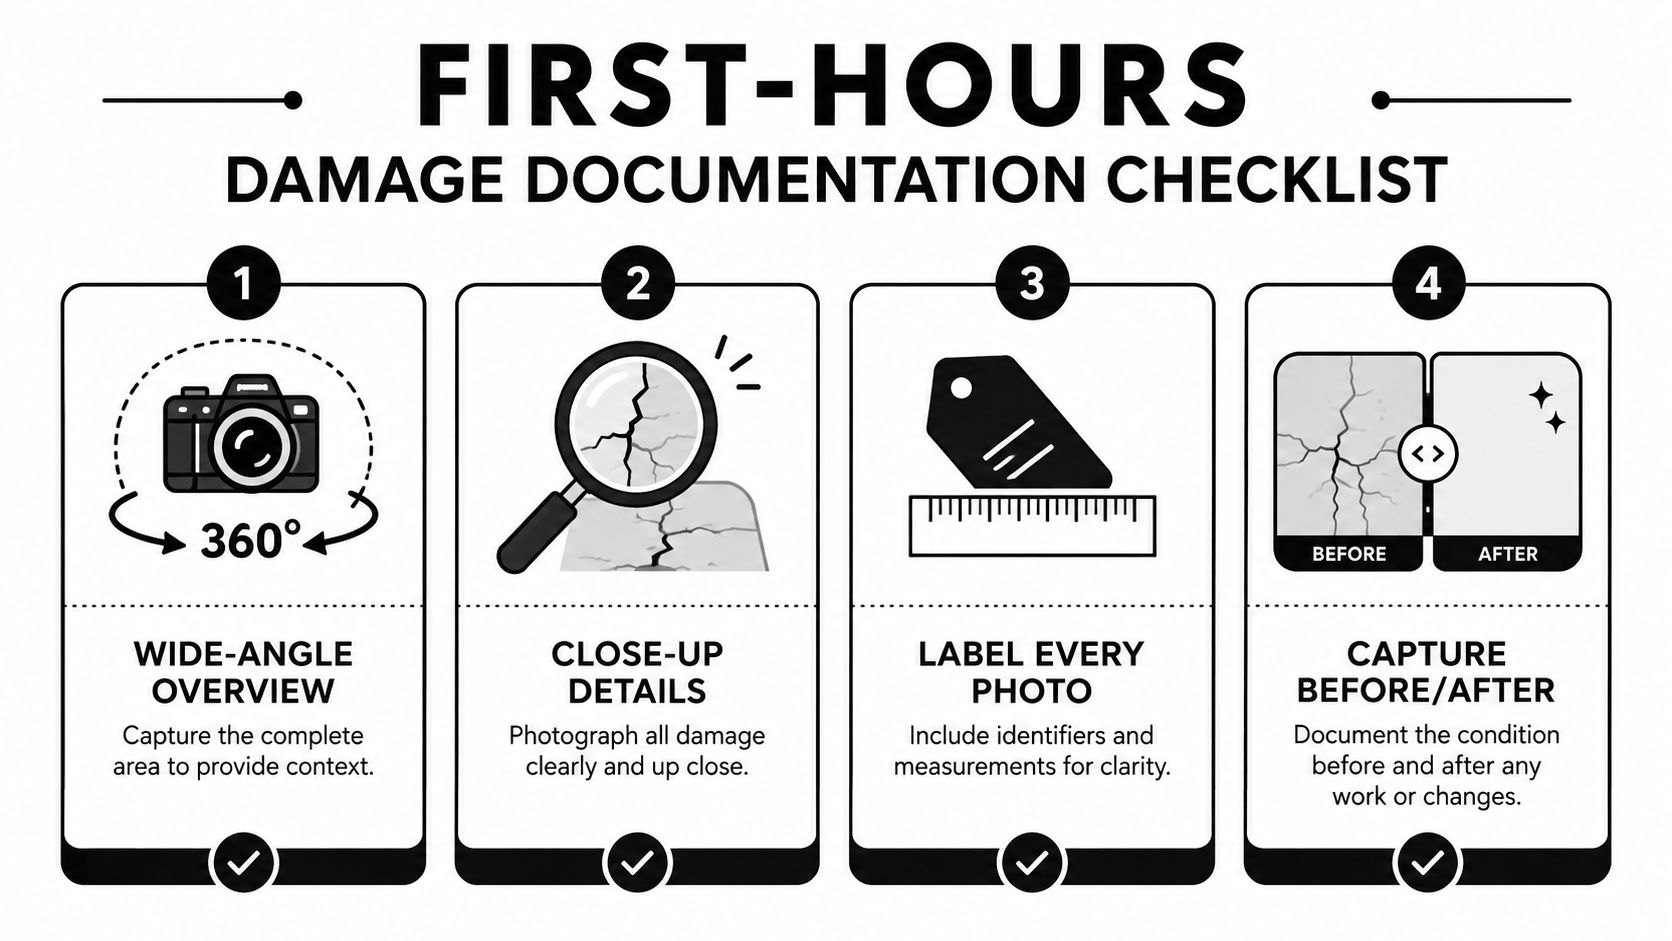
Start with context
Use your phone's native camera and capture a sequence that an unfamiliar person can understand.
- Shoot wide first. Stand at the entrance and record the entire room. Move to opposite corners and photograph each wall, the ceiling, floor, windows, doors, and nearby undamaged areas.
- Move closer. Photograph water lines, blistered paint, soot patterns, cracked materials, lifted flooring, broken fixtures, and damaged contents.
- Show scale. Place a ruler or another recognizable object beside cracks, stains, holes, or damaged edges. Don't place anything into a hazardous area just for a photograph.
- Record a walkthrough. Narrate the room, location, visible condition, and apparent source without guessing about coverage or cause. Say what you know, not what you assume.
Lighting matters. Turn on safe room lights, avoid glare, and take additional images from an angle when a flash washes out a stain or texture. Keep the original files, including metadata, and upload copies to secure cloud storage rather than leaving the only evidence on a phone that could be lost in the same event.
Build a preliminary inventory
Create a working list while the details are visible. Record the item description, room, condition, brand, model, serial number, purchase date, and available receipt or account record. Don't focus only on expensive property. Kitchen contents, clothing, tools, furniture, electronics, and stored items can all belong in the file.
Use a simple log:
| Field | Example entry |
|---|---|
| Date and time | Date and time of observation |
| Location | Kitchen, east wall, lower cabinet |
| Condition | Swollen panel, visible staining |
| Action | Photograph taken, item separated |
| Person involved | Owner, contractor, adjuster |
| Supporting file | Photo name, invoice, email |
If you must move an item, photograph it in place first, label it, and keep damaged parts together when safe. A consistent before-and-after record is more useful than a folder full of unlabeled images. For practical guidance on creating a usable visual record, follow this before-and-after photo documentation guide.
Write notes the same day. Memory fills gaps, changes times, and forgets small items. Your first record should state what you observed, when you observed it, who was present, and what changed afterward.
Building a Complete Claims File That Stands Up to Review
A strong file lets an adjuster trace each claimed item or repair from the original condition to the requested payment. Don't send a random collection of phone photos and receipts. Build a record with a clear index, consistent filenames, and a separate place for open questions.
Make the inventory verifiable
For household contents, include the details that establish ownership, value, identity, and condition. A solid inventory includes item descriptions, serial numbers, purchase dates, purchase prices or receipts, current value or replacement cost, location in the home, and photos tied to each entry (household claim file guidance).
For valuable property, one proof type often isn't enough. Preserve receipts, credit card or bank records, appraisals, manufacturer serial numbers, and photographs showing the item inside the home. These records support ownership, value, and pre-loss condition, not merely the fact that an item is missing (valuable-item documentation guidance).
Use a spreadsheet with one row per item and a unique ID. For example, KIT-014 could identify a damaged kitchen appliance. Name the related files KIT-014_before.jpg, KIT-014_receipt.pdf, and KIT-014_estimate.pdf. That small system prevents an adjuster from having to search through unrelated images.
Organize the file by evidence type
A practical digital structure looks like this:
- 01 Notice and policy: claim number, policy information, loss notice, and relevant correspondence.
- 02 Initial conditions: original photos, videos, written observations, and source documentation.
- 03 Inventory: spreadsheet, receipts, account records, serial numbers, and item photographs.
- 04 Mitigation: work authorizations, daily logs, moisture records, invoices, and disposal records.
- 05 Estimates: contractor scopes, revisions, measurements, material details, and explanations for changes.
- 06 Communications: emails, letters, call notes, information requests, and responses.
- 07 Proof of loss: insurer forms, supporting schedules, and submission confirmation.
Keep originals read-only when possible. Make working copies for annotations, and never overwrite an original photograph or estimate. If a scope changes, save a new version and write why the change occurred.
Texas guidance explains that CLUE reports can retain claim history for the past 7 years, including the date of loss, loss type, amount paid, policy number, claim number, and insurer name (Texas property claim history guidance). That long record makes accuracy important beyond the current settlement. Claims data can also be used in broader administrative systems for auditing, fraud detection, pricing, and analysis, as described by NIH's overview of claims data.
Before submission, compare every line in your inventory with a photograph, ownership record, estimate, or explanation. For a practical review of insurer-facing records, consult PIA Southern Alliance claims advice and use this documentation requirements checklist.
Handling Emergency Mitigation While Preserving Your Claim
Emergency mitigation is where good advice often becomes useless. You can't leave a broken pipe running while waiting for an adjuster, and you can't leave a storm opening exposed while hoping someone arrives before the next rainfall. The property needs protection, but the original condition must still be preserved as evidence.
Record the reason for urgent work
Before extraction, board-up, demolition, deodorization, or temporary roof work begins, capture the visible condition if it's safe. Photograph the source, affected materials, spread pattern, damaged contents, and areas that could suffer secondary damage.
Then create a mitigation record. Note who you called, when they arrived, what they observed, what they recommended, what they did, and which materials they removed or protected. Ask for itemized invoices, equipment records, moisture readings where relevant, photographs, and written explanations of why each emergency step was necessary.
The rule is simple: Prevent further damage, but preserve the evidence of what existed before prevention work began.
Send prompt written notice to the insurer using the contact method required by the policy. Keep the confirmation, claim number, and every response. If nobody answers, record the attempt and continue the necessary safety work. You're building evidence that the mitigation decision was reasonable, not waiting passively for permission while damage spreads.
The emergency water mitigation guidance can help property owners organize that response. For water losses, document the leak source, shutoff action, extraction, affected materials, drying setup, and any disposal. For fire losses, record the areas before soot removal and retain invoices for board-up, odor treatment, cleaning, and damaged-material removal. For storm losses, photograph openings and temporary coverings before and after installation.
A short video can connect separate photographs into one timeline. Narrate the date, location, visible condition, and work underway. Don't speculate about whether the policy covers the loss. Describe facts and preserve the contractor's technical findings.
The following video provides additional visual context for documenting a plumbing repair while work is underway:
Separate emergency work from permanent repairs
Emergency mitigation stabilizes the property. Permanent repair restores it. Keep those scopes separate in estimates and invoices so the insurer can see what happened immediately and what work was proposed later.
Don't discard damaged items unless safety, contamination, or an authorized disposal process requires it. When disposal is unavoidable, photograph the item thoroughly, record its description and location, retain any sample that professionals say is safe to preserve, and keep the disposal documentation. Your file should explain why the item could not remain in place.
This approach protects both sides of the problem. The building receives timely protection, and the claim file shows the original condition, the emergency decision, the work performed, and the cost trail.
Working Effectively with Adjusters and Restoration Professionals
An adjuster can process a clear file faster than a scattered one. Send a concise loss summary, a dated photo index, the preliminary inventory, mitigation invoices, and a communication log. When the insurer requests information, answer each question in the same order and identify the exact file supporting each response.
Don't argue from emotion or submit unsupported conclusions. State that water reached a specific wall, that a contractor removed a specific material, or that a receipt supports a specific item. If you disagree with a scope decision, explain the missing evidence and request the decision in writing.
A restoration professional should document the property independently, not perform cleanup alone. Ask for photographs before work, moisture or damage findings where applicable, daily activity notes, equipment records, itemized invoices, and a scope that distinguishes emergency mitigation from reconstruction. A contractor who communicates clearly with the insurer can reduce duplicated requests, but you still need to retain your own complete file.
For Phoenix-area property owners, Restore Heroes provides disaster restoration services for water damage, fire and smoke damage, mold removal, and trauma or biohazard cleanup, with documentation integrated into the assessment and mitigation workflow. That can be useful when the loss requires immediate action and the owner can't safely manage photography, drying, cleaning, and records alone.
Use this final readiness check before sending the claim package:
- Timeline: Every major event has a date and time.
- Condition: The file shows the loss before mitigation and the work afterward.
- Ownership: Contents have records supporting identity and possession.
- Costs: Estimates and invoices are itemized.
- Communication: Calls, emails, requests, and responses are preserved.
- Versions: Scope changes show who changed them and why.
Your goal isn't to overwhelm the adjuster. It's to remove avoidable uncertainty.
Common Documentation Mistakes and How to Avoid Them
The most damaging errors are predictable. Owners wait to report, photograph only the obvious damage, discard contents before inspection, save vague invoices, or reconstruct dates from memory. Each gap gives the insurer a reason to ask for clarification instead of moving the file forward.
Proof-of-loss timing deserves special attention. A sworn proof of loss is commonly required within 60 days of an insurer's written request for standard homeowners policies, although some policies count from the date of loss. Commercial property policies often use 90 days, while NFIP flood policies require a signed and sworn proof of loss within 60 days of the date of loss (proof-of-loss deadline guidance). Your policy controls, so read the form and request clarification in writing if the deadline is unclear.
Before submission, check:
- Dates: Photos, invoices, notes, and communications tell the same timeline.
- Inventory: Each item has an identity, location, condition, and supporting evidence.
- Mitigation: Emergency work includes the reason, provider, date, scope, and invoice.
- Receipts: Originals or reliable copies are preserved.
- Proof of loss: The form is complete, signed as required, supported, and submitted on time.
- Copies: You have retained the full package and submission confirmation.
Never sign a sworn statement you haven't reviewed carefully. If the loss is complex, disputed, or commercially significant, obtain appropriate professional advice before submitting or accepting a settlement.
If you're facing water, fire, mold, or biohazard damage in the Phoenix metro area, Restore Heroes can document the condition, perform necessary mitigation, and maintain organized records for the insurance process. Visit Restore Heroes to request help with the next safe, documented step.